The 7-Day Expense Tracking Challenge (See Where Your Money Really Goes)
Try this simple 7-day expense tracking challenge to finally see where your money goes and build a more accurate budget with confidence.

Written by Ali Usman
Updated July 11, 20266 min read
How to read this guide
- Who this is for
- Try this simple 7-day expense tracking challenge to finally see where your money goes and build a more accurate budget with confidence.
- Country / market
- General guidance; check local rules, prices, and currency
- Last substantive update
- Research type
- Calculation and desk research
- Sources checked
- Citations are placed beside the claims they support
- Key assumptions
- Worked amounts are examples, not promised savings; local costs and circumstances vary.
On this page
- Why a single week is enough
- Pick how you'll record it (then keep it stupidly simple)
- Record everything — especially the small stuff
- On day 7, add it up and look for the leaks
- What people tend to discover
- Where the experiment goes wrong
- Your 7-day tracking checklist
- Keep it in perspective
- Questions people actually ask
- Do I need an app for this?
- What if I forget a day?
- What do I do with the results?
- Next step
Most budgets don't fall apart because someone's bad at maths. They fall apart because the numbers were guesses from the start. You think you spend about $40 a week on food and "not much" on little extras — and then the month ends and the bank balance disagrees. Tracking every penny for just seven days swaps those guesses for the real figures. It's short enough that you'll actually finish it, and revealing enough that it usually changes how you see your money.
Why a single week is enough
You don't need a month of meticulous records to learn something useful. A week captures your normal rhythm — the commute, the food shop, the midweek treat, the weekend — and that's where the patterns hide. The goal isn't a perfect ledger. It's a wake-up call you can act on.
Pick how you'll record it (then keep it stupidly simple)
Three options, all fine:
- Notes app on your phone — fastest, always with you.
- A scrap of paper in your pocket — works if you'll actually use it.
- A simple sheet — the expense tracking template gives you ready-made columns if you like structure.
Whatever you choose, the rule is the same: write it down within a minute of spending, before you forget. Memory is exactly the thing that lies to you here.
Record everything — especially the small stuff
The big payments (rent, a shop, a bill) you already know about. It's the small, frictionless taps that quietly add up: the coffee, the app subscription that renewed, the "I'll just grab a snack." Catch all of them. A rough note of the amount and what it was for is plenty — no need for categories yet.
On day 7, add it up and look for the leaks
Total it, then group it loosely: essentials, food, transport, fun, random. You're hunting for two things — a category that's bigger than you'd have guessed, and small repeat spends that don't really buy you much. That's your map for what to adjust.
What people tend to discover
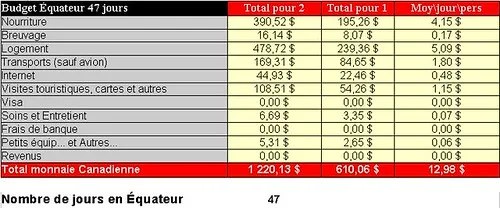
Totalled up, a typical week often looks like this — and it's the bottom cluster, not the big items, that makes people pause (illustrative numbers, 2026):
| Spend | Amount | Expected? |
|---|---|---|
| Groceries | $48 | yes |
| Transport | $22 | yes |
| One takeout | $25 | yes |
| Three coffees out | $9 | the leak |
| Two impulse snacks | $6 | the leak |
| A forgotten subscription | $8 | the leak |
| Week total | ~$118 | ~$23 "invisible" |
Real-life example
A common week looks something like this: groceries $48, transport $22, three coffees out $9, two impulse snacks $6, a forgotten $8 subscription that renewed mid-week, and one $25 takeout. The takeout and groceries are no surprise — but the $23 of coffees, snacks, and the stray subscription is the part that makes people pause. These are illustrative numbers; your leaks will be your own.
Where the experiment goes wrong
- Only logging the big stuff and skipping the $2 bits — that's where the lesson lives.
- Waiting until bedtime to remember the day's spending (you won't).
- Judging yourself instead of just recording. This week is data, not a verdict.
- Stopping after three days because it "looks fine."
Your 7-day tracking checklist
Simple checklist
- Choose one place to record spending
- Write down every purchase within a minute
- Include the tiny taps, not just the big bills
- Note the amount and a few words on what it was
- On day 7, total everything up
- Group it loosely and circle the surprises
Keep it in perspective
When to be careful
Seven days is a snapshot, not the whole story — a week with a big one-off cost can look scary and a quiet week can look rosy. Use it to spot patterns, not to make drastic decisions off a single sample. This is educational, not personal financial advice.
Questions people actually ask
Do I need an app for this?
No. A phone note or a scrap of paper works perfectly. The template just saves you setting up columns.
What if I forget a day?
Note it and carry on — don't restart. An almost-complete week still tells you plenty.
What do I do with the results?
Feed them straight into your monthly budget plan so your categories match real life instead of guesses.
Next step
Once you've got real numbers, they're far more useful inside a plan than on a scrap of paper. Roll them into a beginner monthly budget, see how it shifts budgeting a small salary, or browse more in Budgeting.
Keep exploring
Where to go next if this guide was useful.
About the author
Founder and sole author, BudgetCalm
I started paying real attention to money in 2016 and have run my own budget since 2018. I built BudgetCalm to cover what most finance sites skip — groceries, no-spend months, and making a tight budget actually hold. I've written 100+ guides and built the 6 calculators on this site because I couldn't find free ones that handled real household numbers without a signup wall. I cover budgeting, grocery savings, no-spend challenges and frugal living. I don't cover investing, tax, credit cards, loans, insurance or debt management.
Disclaimer: This content is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial professional before making financial decisions.
Get practical budgeting tips delivered to your inbox
Calm, beginner-friendly guides for budgeting and saving money, straight to your inbox.
No spam. Educational money-saving tips only. Unsubscribe anytime.